Buying in Sterling Grove, Surprise AZ: 10 Questions About the Community and the Mortgage
Sterling Grove Surprise AZ: Buyer and Mortgage Questions – Joe Hansen Mortgage Broker NM:S 217716
A straight look at Sterling Grove for buyers who have already done their homework, plus the financing questions that come up in a gated golf community and rarely get answered anywhere else.
Something has shifted in how people buy homes out here, and the real estate side has noticed it before the mortgage side did.
Look at what is happening inside Sterling Grove. There are agents working that community on a flat fee instead of a percentage, and their reasoning is hard to argue with. Buyers now find their own homes. They have walked the models, watched the drone footage, compared the floor plans, and read the HOA documents before anyone picks up a phone. When the client has already done half the job, charging a full traditional commission starts to look like a habit rather than a price.
The same logic applies to a mortgage, and most lenders would rather you did not think about it too hard.
If you are a well-qualified buyer with strong credit, documented income and real reserves, you are the least expensive borrower in the entire system to underwrite. Your file closes on time. It does not require three rounds of conditions. You know what you want. You should be getting the sharpest pricing available, and in a lot of cases you are not, because you walked into a retail bank or the builder’s sales office and were quoted from a single menu.
Here is the structural difference, and it is not a marketing claim. A retail loan officer at a bank or a builder-affiliated lender can offer you what that one institution is selling that day. As an independent broker, I submit your file to a number of wholesale lenders and they compete for it. That does not guarantee any particular outcome on any particular file, and I will never tell you it does. But when several lenders price the same borrower on the same day, one of them is usually sharper than the others, and having that comparison in front of you costs you nothing.
So my offer for Sterling Grove buyers is simple. Before you accept the builder’s financing or sign with whoever your bank handed you, send me the Loan Estimate. I will read it line by line and tell you where it is strong and where it is not. If what you already have is the better deal, I will tell you that too, and you will have lost nothing but the time it took to email me a PDF.
The rest of this page is the information I find myself repeating to buyers looking at this community. Five questions about Sterling Grove itself, and five about the money.
Part one: the community
What Sterling Grove actually is, how it is put together, and the parts buyers most often get wrong.
1. Where is Sterling Grove and what kind of community is it?
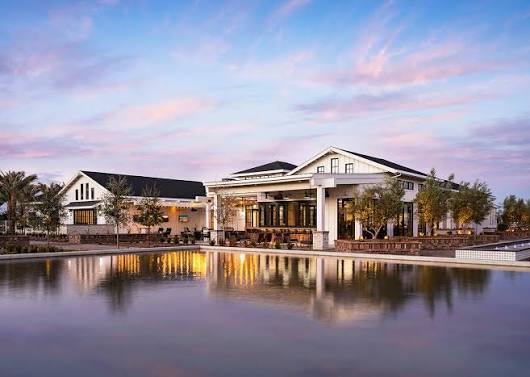
Sterling Grove is a staff-gated, master-planned golf community in Surprise, Arizona, 85388, developed by Toll Brothers. It occupies roughly 780 acres against the foothills of the White Tank Mountains, west of the Loop 303 corridor, which is the piece that makes the location work. The 303 has changed the commute math for the whole west side of Surprise over the last several years, and the Prasada retail area nearby has filled in the shopping, dining and everyday services that used to require a drive east.
The community is built around an 18-hole Nicklaus Design golf course with golf operations run in association with Troon, and a private clubhouse that functions as the social center of the place. Homes fall within the Dysart Unified School District, though school assignments do change and families should confirm the boundary for a specific address directly with the district rather than relying on a listing sheet.
Two things distinguish it from most of what the West Valley has built in the last decade. First, the amenity package is genuinely country-club scale rather than the standard subdivision pool and ramada. Second, it is staff-gated, meaning an actual person at the gate rather than a code pad. If you are moving here from out of state, ask specifically about guest access procedures, contractor entry and how moving trucks are handled, because those rules vary considerably from community to community and are easy to overlook until the week you need them.
The Sterling Grove Golf & Country Club site is the best source for current facilities and club programming. There is also a resident-maintained community site with a living here section that gives you a feel for day-to-day life inside the gates in a way builder marketing never will.
2. Is Sterling Grove a 55+ community?
No, and this is the single most common misconception I run into.
Sterling Grove is not exclusively age-restricted. The master plan includes all-ages neighborhoods alongside designated active-adult options. Part of the confusion is geographic. Surprise has a long association with age-restricted living, Sun City Grand is right there, and buyers reasonably assume that a golf community on this side of town follows the same model. Sterling Grove does not.
What that means practically is that you cannot assume either way. If you are specifically looking for an age-restricted section, you need to confirm that the particular home sits inside one. If you have children at home and you are worried about restrictions, you need to confirm the opposite. The answer lives in the recorded CC&Rs for that section, not in a sales conversation, and it should be verified before you write an offer rather than after.
This matters for financing too, though less dramatically than people expect. Age-restricted status does not by itself disqualify a property from conventional, VA or FHA financing. It does show up in appraisal and project review, and it narrows the resale pool later, which is worth thinking about even if you plan to stay a long time.
3. What are the amenities, and is golf membership included with the home?
The amenity list is the reason most people end up here. It currently includes the 18-hole Nicklaus Design course, a private clubhouse, three resort-style pools, a fitness center with a separate movement studio, a full-service spa, tennis and pickleball courts, indoor and outdoor dining including a restaurant, a grab-and-go market, and parks, gardens, water features and walking trails threaded through the community.
Now the part that surprises buyers: owning a home here does not automatically hand you full golf privileges.
In club communities generally, there are layers. There is the master association that maintains the common areas and gives you the baseline community access. There is often a social or club membership covering the clubhouse, dining and fitness side. And there is golf, which usually carries its own initiation cost and ongoing dues, and which may or may not have availability at the moment you want it.
Those layers are not always obvious from a listing or a model home tour, and they can add a meaningful amount to what you actually pay every month. Before you fall in love with a floor plan, get the current membership documents and read what is mandatory versus optional, what transfers with the property, what does not, and whether there is a waiting list for the category you want. Membership structures at private clubs get restructured periodically, so a figure a neighbor quotes you from three years ago may no longer be the deal on the table.
4. What kinds of homes are available in Sterling Grove?
There are three distinct paths in, and they behave very differently in a transaction.
To-be-built Toll Brothers homes. You select a lot, a plan, and your finishes. Maximum personalization, longest timeline, and the path where lot premiums and design center upgrades can move the final number a long way from the advertised base price.
Builder quick move-in homes. Already under construction or complete, with selections made. Faster, often where the most aggressive builder incentives get attached, and less flexible.
Resale homes. Purchased from a prior owner. These are frequently undervalued by buyers comparing them against a builder base price, because a resale often already includes the things a new home does not: finished backyard landscaping, a pool or spa, window coverings, upgraded lighting, appliances, built-in storage and completed patios. In this climate, backyard landscaping and a pool on a new build is not a small line item. Compare finished cost to finished cost.
The product itself spans several collections, from smaller low-maintenance villas up through large single-family homes, in one- and two-story plans, with floor plans that generally run from around 1,300 square feet at the small end to over 4,000 at the top. Golf-course frontage and mountain-view lots carry premiums. Exact plans, sizes, pricing and availability shift constantly as sections release and sell out, so treat any number you read online, including mine, as a starting point and confirm current inventory directly.
For current listings and community-specific real estate help, Sterling Grove residents maintain a vendor directory listing local real estate professionals, including agents with RE/MAX Desert Showcase who work the community regularly. I am happy to work alongside whichever agent you choose. My job starts where theirs leaves off.
5. What HOA, club and transfer fees should I expect, and how do I verify them?
I am not going to publish dollar figures here, and I would be skeptical of any page that does.
Fee schedules in a club community change. Assessments get adopted. Membership categories get restructured. A number that was accurate when someone wrote a blog post two years ago can be meaningfully wrong today, and you are the one who signs the closing documents. What I can give you is the complete list of what to ask about, which is more useful anyway:
- Master HOA dues, and the billing frequency
- Sub-association or neighborhood dues, if the section has them
- Club or social membership charges
- Golf initiation fees and ongoing golf dues, if you want golf
- Transfer fees, capital contributions or reserve contributions due at closing
- Resale disclosure and document preparation fees
- Any special assessment currently adopted or under discussion
- What each of these covers, and what is explicitly excluded
Get it in writing. On a resale, the HOA resale disclosure package is the authoritative document and Arizona law entitles you to it. On a new build, ask the sales office for the current fee schedule and the club membership schedule as separate written items. Verbal estimates from anyone, including me, are not something to budget against.
There is a second reason to chase this down early, and it is the bridge into the financing half of this page: some of these charges are not just a lifestyle expense. They affect whether you qualify, and for how much.
Part two: the financing
This is the part the real estate listings do not cover, and where a community like this differs from a standard subdivision purchase.
6. Do I have to use the builder’s lender, and is the incentive actually worth it?
You can generally choose your own lender. What you may not be able to do is keep the incentive while doing it, because builder credits are commonly conditioned on financing through the affiliated lender and sometimes on using preferred title as well.
That puts a real decision in front of you, and the way most buyers evaluate it is wrong. They compare the size of the credit. A $20,000 incentive sounds decisively better than no incentive, so the conversation ends there.
The credit is one number in a transaction with about eight of them. What you actually need to compare, on complete Loan Estimates side by side:
- Interest rate and APR
- Discount points, and whether they are being charged to manufacture the advertised rate
- Lender, underwriting and processing fees
- The credit itself, and any restriction on what it can be applied to
- Whether a buydown is temporary or permanent, and what the payment becomes when a temporary one expires
- Mortgage insurance, if applicable, and how it is structured
- Monthly principal and interest
- Total cash required at closing
- Total cost over the period you realistically expect to own the home
I have seen incentives that were unambiguously the best available deal and I told those buyers to take them. I have also seen a large credit sitting on top of a rate and a fee structure that gave most of it back within a few years. Both exist. The only way to know which one you are looking at is to run the comparison, which takes me about twenty minutes and costs you nothing.
One practical note on timing: request the Loan Estimate from the builder’s lender in writing and early. You are entitled to it, and having it in hand before you are emotionally committed to a specific lot makes the whole conversation easier.
7. Do Sterling Grove HOA and club dues affect my mortgage qualification?
Yes, and in a community with dues at this level it is not a rounding error.
When a lender calculates your debt-to-income ratio, required HOA dues are included in your monthly housing expense right alongside principal, interest, property taxes, homeowners insurance and any mortgage insurance. Mandatory club charges tied to ownership are generally treated the same way. Optional golf membership that you elect by choice is handled differently, but the line between mandatory and optional is exactly why you need the documents rather than a verbal summary.
Here is how this goes sideways. A buyer gets preapproved using a generic HOA estimate, shops confidently at that price point, then finds out during underwriting that the true required monthly obligation is several hundred dollars higher than what was modeled. The qualifying number moves. Sometimes it moves enough to matter.
That is avoidable. When I preapprove someone for a club community, I want the real dues in the file from the start, along with actual property taxes for the specific parcel rather than a county average, because Arizona tax figures on new construction can lag behind the finished value for a period and then jump. A preapproval built on real numbers is worth something. One built on placeholders is a guess with a letterhead.
If you want to see what a properly documented preapproval looks like and what Arizona agents expect to see with an offer, I wrote a full walkthrough of the Arizona pre-qualification form, including the lines that listing agents actually read.
8. Can I use a VA loan in Sterling Grove?
Often, yes, and I would encourage eligible veterans not to rule this community out on price assumptions. There is no VA loan limit for a veteran with full entitlement, so the financing reaches further into this price range than most people assume, and the absence of monthly mortgage insurance changes the payment math considerably against a conventional loan at the same price.
Two things need verifying. The first is your entitlement, which depends on your service and on whether you have an active VA loan elsewhere. The second is the property, and this is where Sterling Grove requires a little care. A detached single-family home is generally straightforward. If a particular property is legally a condominium, the project needs to be VA-approved or go through approval, and that is a process with a timeline attached to it. Finding this out two weeks before a scheduled close is not where you want to be.
There is also the practical question of builders and VA offers. Some builder sales teams are less familiar with VA financing than they are with conventional, and occasionally that unfamiliarity gets expressed as reluctance. A veteran with a strong, properly documented preapproval and a lender who will get on the phone with the sales office generally clears that quickly.
I have written a detailed guide to VA loans in Surprise, Arizona, covering entitlement, funding fee exemptions, and how VA offers are received in this market. Luke Air Force Base is close enough that I work with a steady number of active-duty and retired buyers on this side of the valley.
9. Are Sterling Grove villas financed like a house or like a condo?
This is the most technical question on the page and the one that has cost buyers the most money when it gets missed.
“Villa” is a marketing and lifestyle description. It usually signals a smaller, lower-maintenance home, often with exterior maintenance handled by the association. It tells you nothing definitive about how a lender will treat the property.
What matters is the legal classification recorded on the property, which could be:
- A detached single-family residence on its own lot
- An attached home, such as a townhome, on its own lot
- A condominium unit, where you own the airspace and share ownership of the structure and land
If it lands in that third category, several things change at once. The lender must review the project itself, not just you. That review looks at owner-occupancy ratios, investor concentration, budget and reserve adequacy, insurance coverage, any litigation, and the percentage of units owned by a single entity. Loan programs available to you may narrow. Down payment requirements can differ. Conventional pricing carries an adjustment for condominiums at certain loan-to-value ratios. And as noted above, VA and FHA each have their own project approval requirements.
None of that is a reason to avoid a villa. Plenty of them finance without incident. It is a reason to confirm the classification in the first conversation instead of discovering it in underwriting, when your options have narrowed and your timeline has not.
When a buyer sends me a property, confirming the legal property type is one of the first things I check. It takes a few minutes and it has saved several transactions I can name.
10. How do I buy in Sterling Grove before selling my current home?
A large share of buyers here are moving from somewhere else, often from another state, sometimes from elsewhere in the valley, and almost always with substantial equity sitting in a house they still own. The question is how to get from there to here without either carrying two mortgages indefinitely or writing an offer so weighed down with contingencies that nobody takes it seriously.
The realistic options:
- Qualify carrying both. If your income and reserves support both payments, this is the cleanest path and makes the strongest offer. On a to-be-built home with a long construction timeline, it is often the most practical too.
- Draw a HELOC on the departing residence. Taken out before you list it, this can fund the down payment. The critical detail is sequencing, because the line must be in place before the house goes on the market.
- Bridge financing. Short-term borrowing against the existing home’s equity. It costs more, and it solves a timing problem that nothing else solves cleanly.
- A sale-contingent offer. Occasionally accepted on a resale, rarely competitive against a clean offer, and generally a nonstarter with a builder.
- Close larger, then recast. Take the loan you can qualify for now, and after the prior home sells, apply a lump sum to principal and have the lender recalculate the payment over the remaining term. Not every loan permits a recast and the fee and minimum vary, so confirm it up front rather than assuming.
There is also a reserve question that gets overlooked at this price point. Lenders want to see assets remaining after closing, and the requirement generally increases with loan size and when you are carrying a departing residence. Running out of documented reserves at the wrong moment is a frustrating way to lose a transaction, especially when a small amount of advance planning would have prevented it.
Map this out before you write an offer, not after. Sequencing is most of the game here, and a plan built in advance is worth more than any rate.
Considering a home in Sterling Grove?
Send me the property address, the estimated purchase price, and any financing proposal you have received. If you already have a Loan Estimate from the builder’s lender or anyone else, I will compare it against what I can source from multiple wholesale lenders and walk you through the differences in plain English.
I can help you:
- Compare the builder’s financing against independent options, line by line
- Read a Loan Estimate you already have and tell you where it is strong and where it is not
- Explain points, credits and the difference between a temporary and a permanent buydown
- Build a full monthly payment estimate using actual taxes and the real HOA and club dues
- Confirm the legal property type before it becomes a problem
- Plan the sequence if you are buying here before selling elsewhere
No obligation, and no pressure to switch. If the offer you already have is the better deal, I will tell you so.
Joe Hansen
Mortgage Broker | Precision Mortgage | NMLS 217716
14155 N 83rd Ave Ste 125, Peoria, AZ 85381
joehansen@precisioninc.org
Mortgage broker serving Surprise, AZ
Why work with an independent broker on a purchase like this
I have been financing homes in the West Valley for 24 years, I teach continuing education on credit to Arizona realtors, and I run this practice myself, which means the person who quotes your loan is the person who structures it and the person who answers the phone when something needs solving at nine o’clock on a Tuesday night.
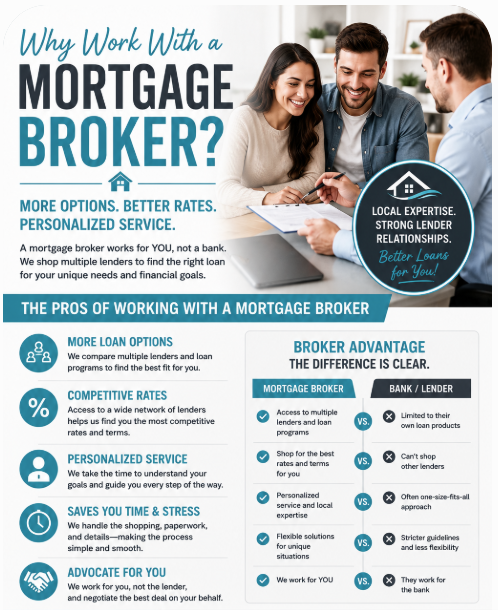
That last part matters more on a purchase like this than it does on a straightforward transaction. A club community purchase has more moving parts: property classification, membership structures, dues that affect qualification, builder timelines, and frequently a home somewhere else that has to sell. Those are not problems that get solved by a call center.
The recognition is nice too. I was recently named the number one mortgage broker in Peoria for 2026 by BusinessRate. But the reason to call is simpler than an award: you are a well-qualified buyer, you have done the work, and you should have more than one lender competing for your loan before you sign anything.
Send me the Loan Estimate. Let me show you what else is out there.
Joe Hansen, NMLS #217716, AZ LO-0911403. Precision Mortgage, 14155 N 83rd Ave Ste 125, Peoria, AZ 85381. This article is provided for general informational purposes only and is not a commitment to lend, an offer of credit, or financial, legal or tax advice. Loan approval is subject to credit review, income and asset documentation, property eligibility, appraisal and current investor guidelines. Interest rates, program availability and terms are subject to change without notice and vary by borrower and transaction. Community details, home collections, amenities, school assignments, HOA dues, club membership structures and fee schedules described here are subject to change and should be independently verified with Toll Brothers, the homeowners association, Sterling Grove Golf & Country Club and the Dysart Unified School District. Joe Hansen and Precision Mortgage are not affiliated with, endorsed by, or acting on behalf of Toll Brothers, Sterling Grove Golf & Country Club, RE/MAX Desert Showcase or any homeowners association. Equal Housing Opportunity.
